Tharisa lifts FY2026 targets for both PGMs and chrome
Dual-metal miner guided 145,000-165,000oz of PGMs and up to 1.65-million tonnes of chrome after a strong finish to FY2025
Tharisa has set FY2026 production guidance of between 145,000 and 165,000 ounces of platinum group metals and between 1.5-million and 1.65-million tonnes of chrome concentrate, an increase on the 138,300 ounces of PGMs and 1.56-million tonnes of chrome it produced in FY2025.
A strong close to the year
Tharisa's fourth-quarter FY2025 performance underpinned the more confident guidance, with PGM output surging 19.7% quarter on quarter to 41,300 ounces and chrome concentrate output rising 2.9% to 407,200 tonnes. "We closed the year on a strong note, delivering robust production results in the final quarter," said chief executive Phoevos Pouroulis, adding that ongoing capital investment was supporting "safety, operational efficiency and sustainability."
A dual-commodity model that spreads risk
Unlike single-commodity chrome or PGM producers, Tharisa mines both from the same open-pit operation at its flagship mine near Rustenburg, giving it exposure to two different demand cycles — stainless steel and industrial demand for chrome, and autocatalyst and jewellery demand for PGMs. That diversification has helped the company keep investing through periods when one commodity's price is weak.
Committing to the mine's future
Alongside the higher guidance, Tharisa disclosed a $547m commitment to transitioning part of its operation to underground mining, with first underground ore originally targeted for the second quarter of 2026. The underground investment is designed to extend the life of the Tharisa mine well beyond its current open-pit horizon.
What it means for South Africa's chrome sector
Tharisa's guidance increase stands in contrast to the retrenchments and smelter idling under way elsewhere in South Africa's chrome industry during the same period, underlining how mining-only chrome concentrate producers — who sell ore rather than relying on their own ferrochrome smelters — have been more insulated from the electricity-cost crisis than integrated ferrochrome producers such as Samancor and Glencore-Merafe.
Sources
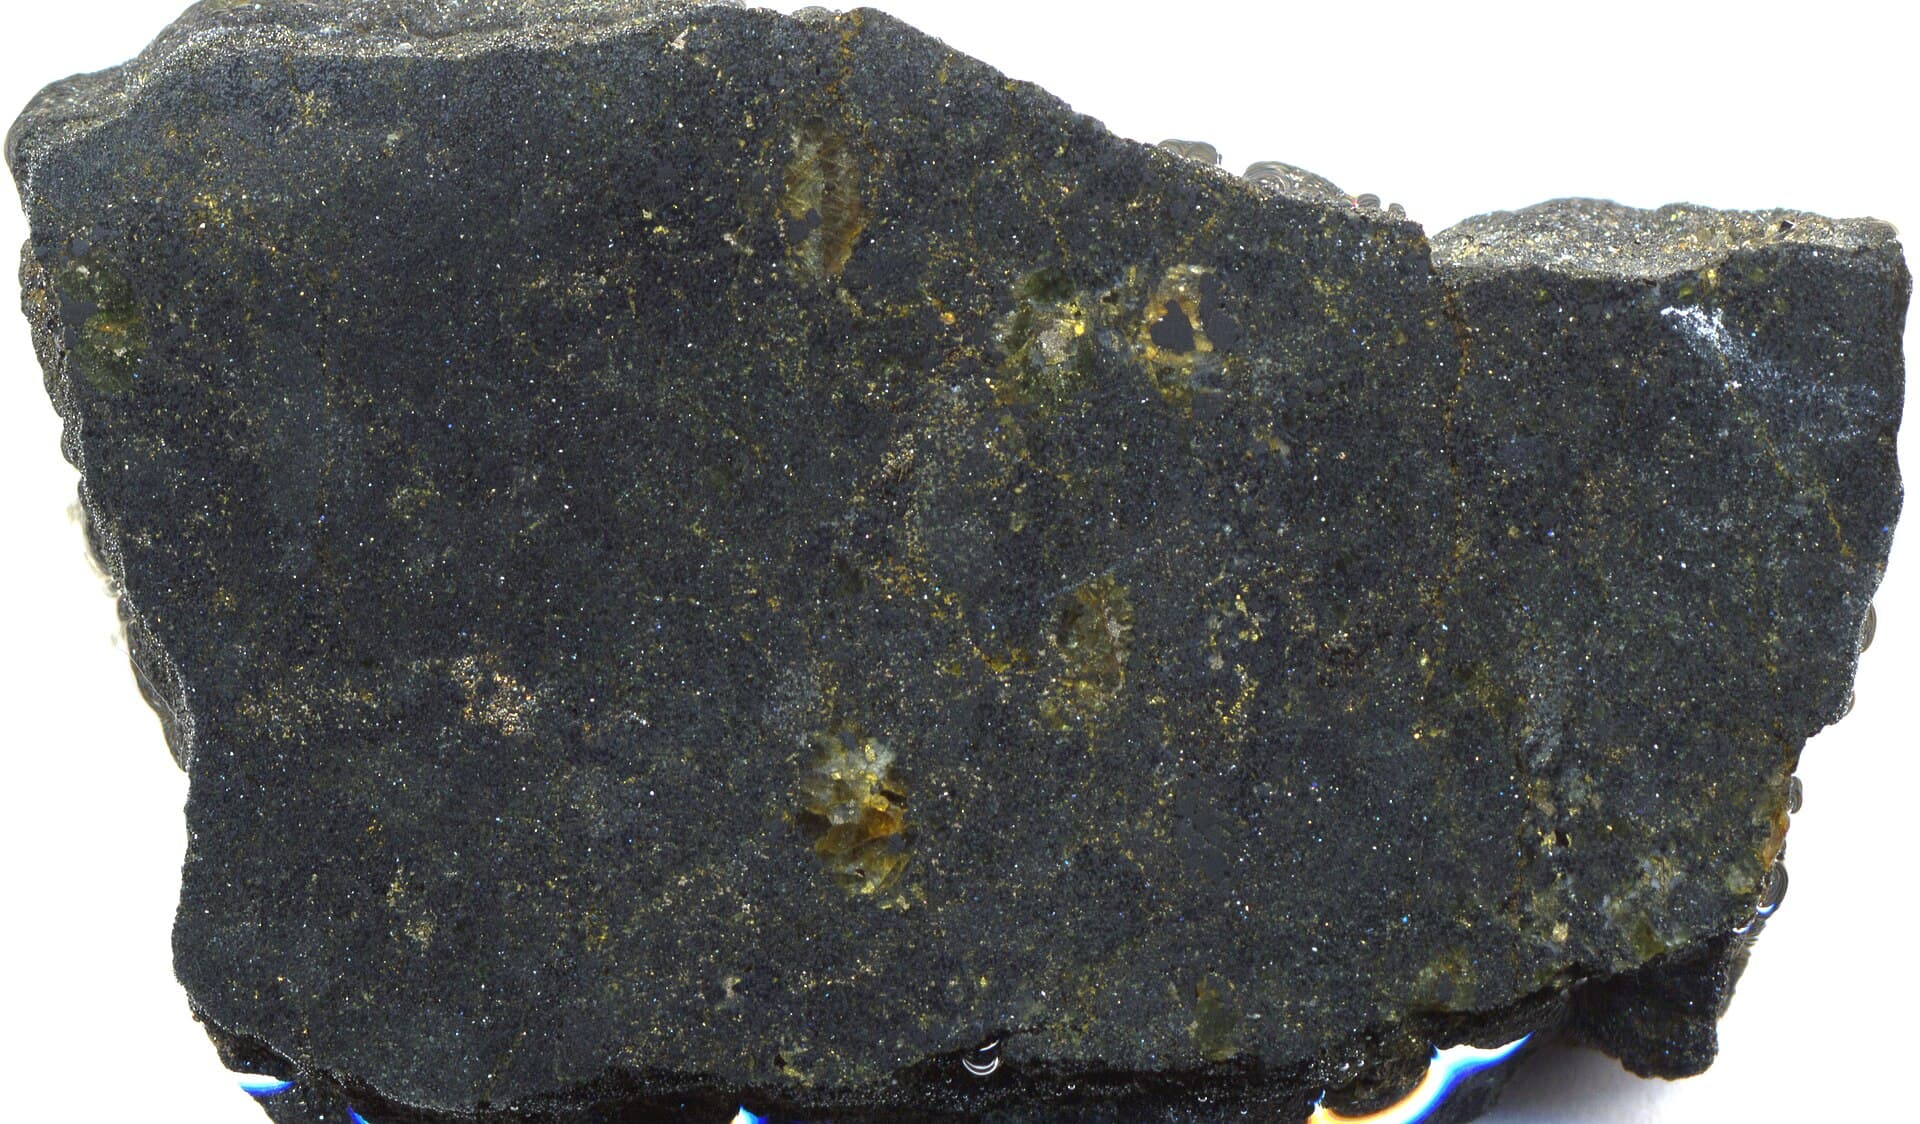
Photo: Chromite-bearing rock from South Africa's Bushveld Complex, the geological formation Tharisa mines for both chrome and PGMs. James St. John, Wikimedia Commons, CC BY 2.0.
Was this useful?
More from MiningWrap
The whole sector in one weekly read.
Deals, policy and markets — every Thursday.
Discussion
Loading comments…