AngloGold Ashanti launches $650m tender to buy back 2028, 2030 and 2040 notes
Early take-up topped 70% on the nearest maturity as the gold miner uses record cash flow to trim future interest costs
AngloGold Ashanti Holdings, the financing subsidiary of the world's third-largest gold producer, launched capped cash tender offers on 30 March 2026 to buy back up to $650m combined of its 3.375% notes due 2028, 3.750% notes due 2030 and 6.500% notes due 2040. By the early tender deadline of 13 April 2026, holders had tendered about 74% of the outstanding 2028 notes, nearly 64% of the 2030 notes, and 26% of the 2040 notes, the last of which was subject to a $50m purchase cap. The offers were due to run until 28 April 2026 unless extended.
Cash-rich miner cleans up its balance sheet
The buyback is a liability-management exercise rather than a response to financial distress: AngloGold Ashanti, like its gold-mining peers, has generated substantially higher free cash flow over the past two years as bullion prices climbed to successive record highs. Retiring bonds ahead of maturity, particularly the higher-coupon 6.5% 2040 notes, reduces the company's future interest bill and simplifies its debt maturity profile at a moment when it can comfortably fund the repurchase from operating cash flow.
A pattern across the sector
The AngloGold tender follows similar debt-management moves by peers including Sibanye-Stillwater, which priced new notes and tendered for older ones in May 2026, suggesting record gold and PGM prices are prompting miners across the board to prioritise balance-sheet clean-up alongside dividends and buybacks. For AngloGold, which operates mines in Ghana, South Africa's neighbouring region, the Democratic Republic of Congo, Tanzania and beyond, a stronger balance sheet also gives it more flexibility to pursue growth opportunities as gold-sector consolidation continues.
What comes next
Bondholders who did not tender by the early deadline retained the option to do so before the final 28 April deadline, though typically on less favourable terms than early participants. The scale of early take-up, particularly on the nearer-dated 2028 notes, suggests investors were keen to lock in the tender premium rather than hold to maturity.
Debt investors who did not participate in the early tender window still had the option to tender before the final deadline, though typically at less favourable pricing, and the strong early uptake on the nearest-dated notes suggested most bondholders preferred certainty over waiting for a potential future refinancing.
Sources
- The Globe and Mail: AngloGold Ashanti Reveals Strong Early Take-Up in $650 Million Note Tender, 14 Apr 2026
- BusinessWire: AngloGold Ashanti Holdings plc Announces Capped Cash Tender Offers for Part of Its 3.375% Notes Due 2028, 3.750% Notes Due 2030 and 6.500% Notes Due 2040, 30 Mar 2026
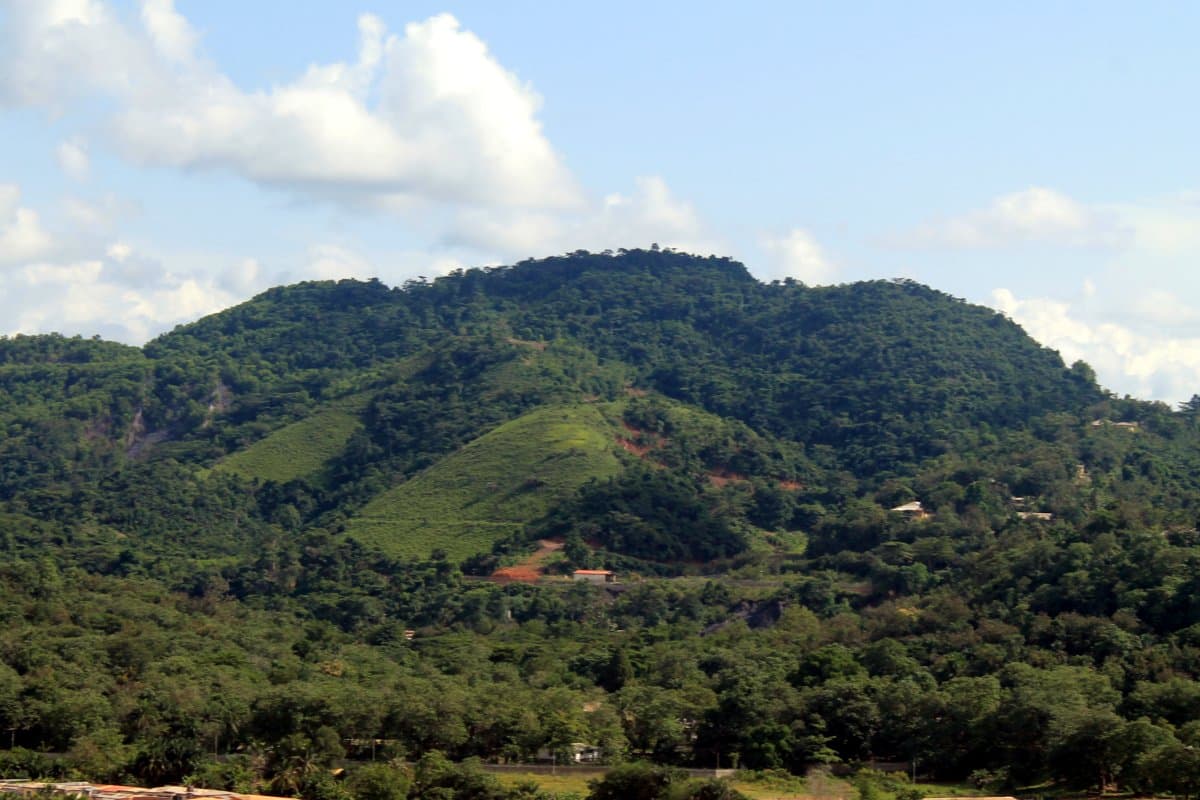
Photo: Obuasi, home to one of AngloGold Ashanti's major Ghanaian gold mines. Kobebigs, Wikimedia Commons, CC BY-SA 3.0.
Was this useful?
More from MiningWrap
The whole sector in one weekly read.
Deals, policy and markets — every Thursday.
Discussion
Loading comments…